
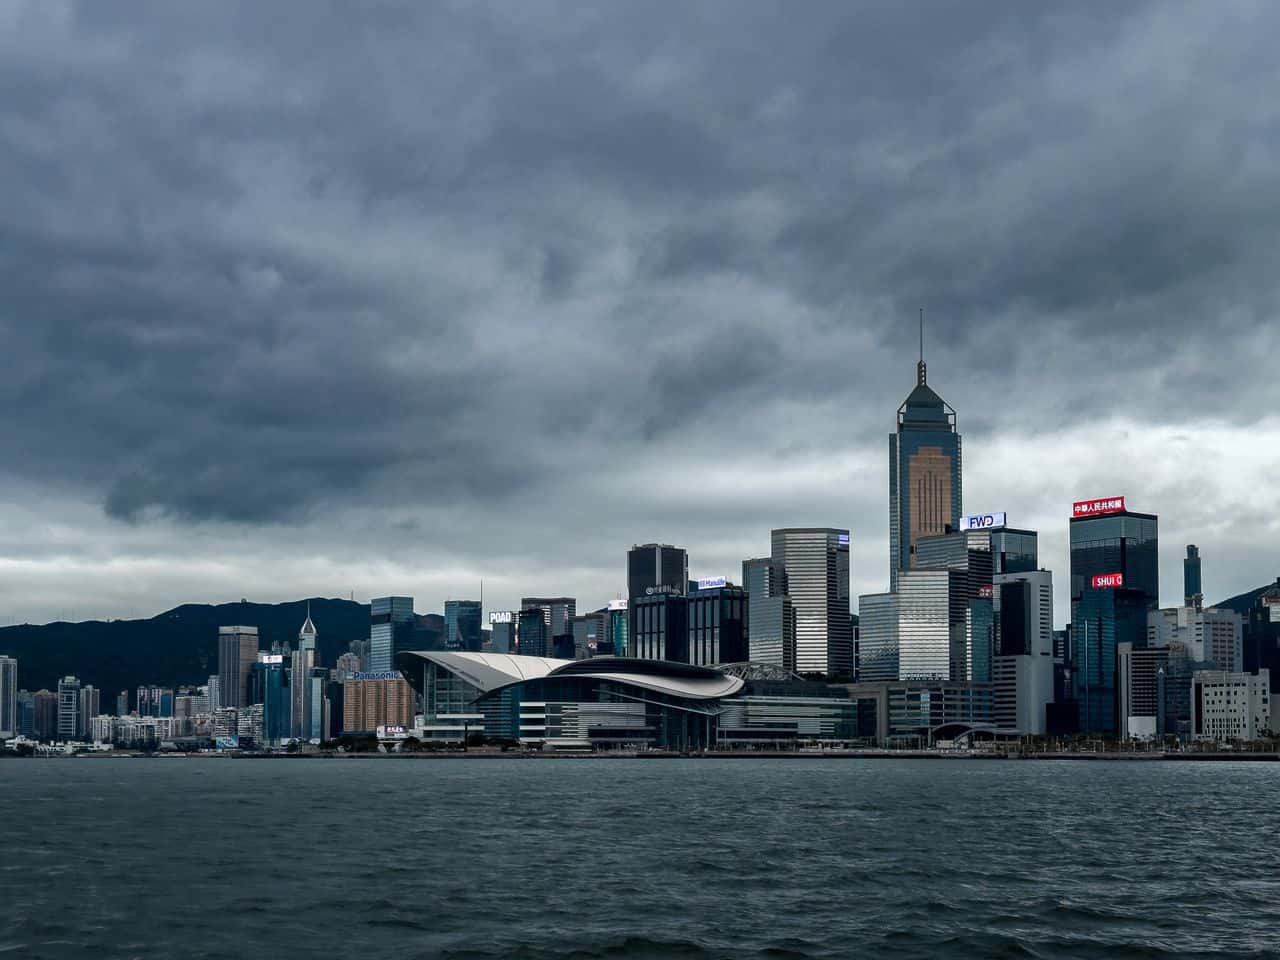
Hong Kong’s latest development in tokenised finance is moving towards everyday institutional use, opening opportunities for flexibility for investors and businesses.
Under the move by the Hong Kong Monetary Authority and Securities and Futures Commission, investment transactions and bank settlement become more closely connected, ushering possibilities to make those capabilities part of how institutions routinely manage cash, invest and meet their obligations.
According to a press release by OneAsset, the developments have relevance beyond Hong Kong. Institutions building tokenised products across markets are examining how new platforms can work with the banks, custodians and investment processes their customers already use.
Tokenised finance presents a related opportunity, as a new investment product becomes more practical when customers can fund it through their existing banking arrangements, maintain reliable records and receive proceeds in a form they can use.
Further, it has been noted that businesses manage cash against a calendar of salaries, supplier invoices, debt repayments and planned investment and temporarily surplus funds may earn a return, although they must become available when obligations fall due.
OneAsset says more closely connected investment and payment systems could improve that balance. Where trading, settlement and access to proceeds are available together, businesses may be able to keep funds invested closer to the point when they are needed.
Relevance to finance leaders
For CFOs and senior finance leaders, Hong Kong’s latest developments in tokenised finance could signal a shift in how businesses manage liquidity, invest surplus cash and meet short-term financial obligations.
By bringing investment transactions and bank settlement closer together, the Hong Kong Monetary Authority and Securities and Futures Commission are advancing an environment where institutions could potentially move between investing and accessing funds more efficiently.
This could give corporate treasurers and CFOs greater flexibility in managing working capital, particularly when balancing returns on temporarily idle cash against the need to maintain sufficient liquidity for payroll, supplier payments, debt servicing and other operational expenses.
The development also raises opportunities for businesses to rethink traditional treasury and investment strategies.
As tokenised financial products become more integrated with existing banking, custody and payment infrastructure, CFOs could explore ways to put surplus funds to work without compromising access to cash when obligations fall due.
However, finance leaders will need to assess the liquidity, settlement reliability, regulatory requirements, custody arrangements and risks associated with these products before incorporating them into corporate treasury operations.
Ultimately, the value of tokenised finance for businesses will depend on whether it can deliver more efficient cash management, improved liquidity visibility and practical returns while preserving the security and predictability of existing financial processes.